Refurbishment Finance: Bridging the Gap Between What a Property Is and What It Could Be
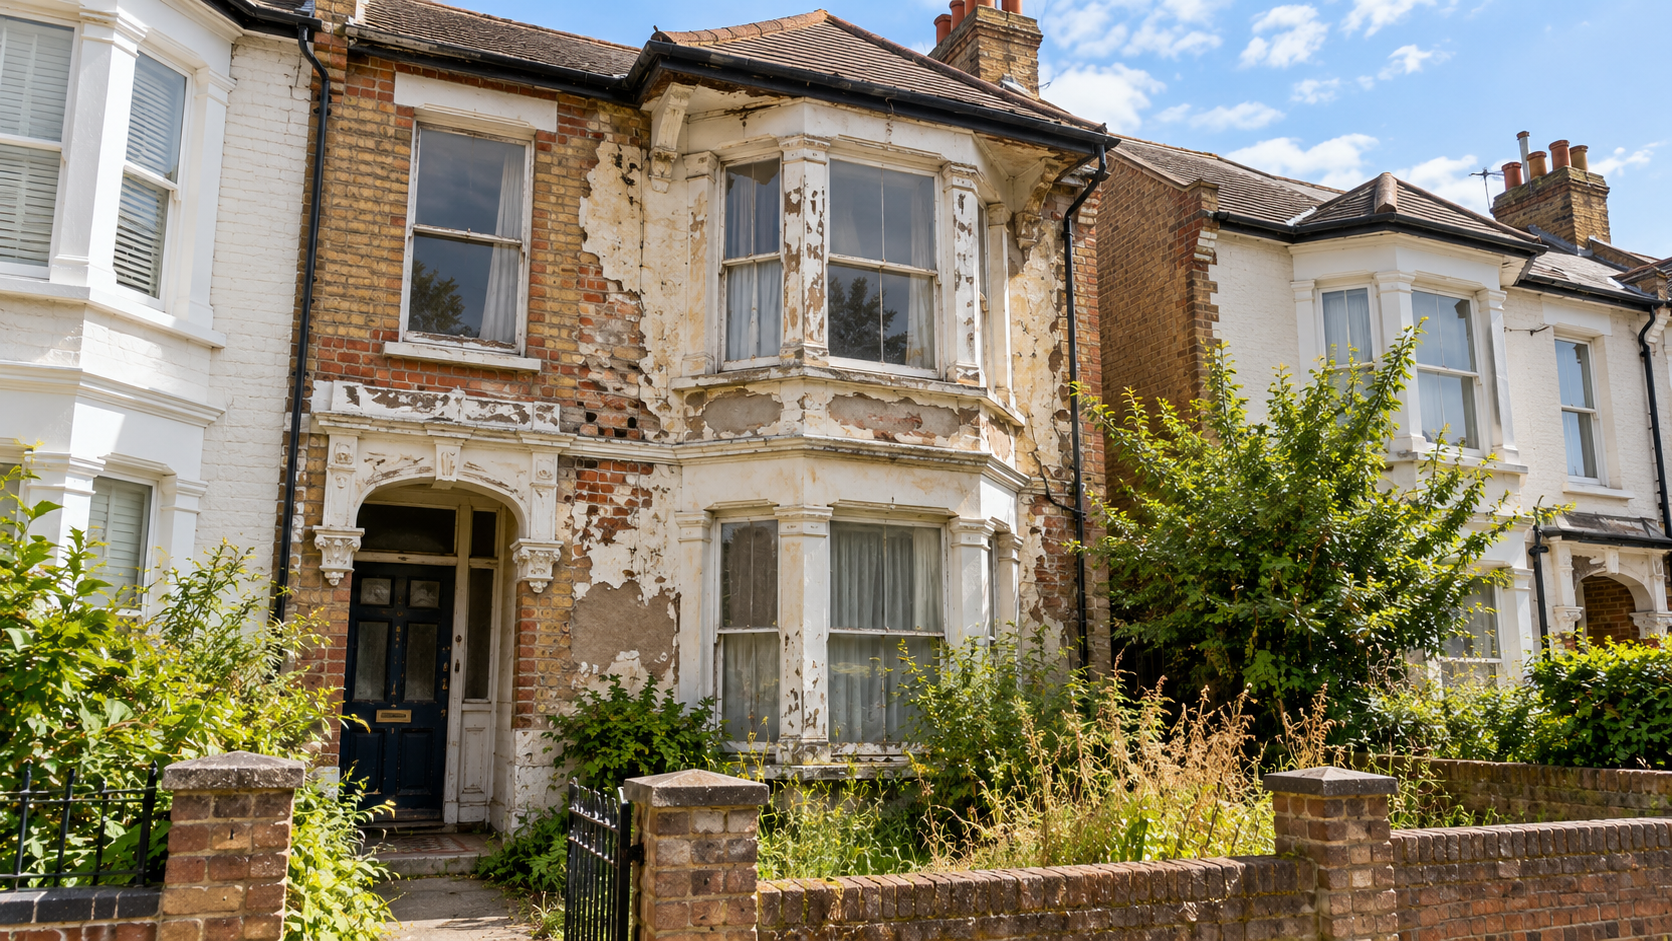
Some of the best investment opportunities in UK property right now are the ones that most lenders will not touch. Properties in poor condition, structurally compromised buildings, flats without functioning kitchens, houses that have been left empty for years. Mainstream mortgage lenders require properties to be in habitable condition before they will lend. If a property does not meet that standard, it is effectively unmortgageable through conventional channels regardless of what it would be worth once the work is done. That is exactly the gap that refurbishment finance is designed to fill. It funds the purchase and the improvement works together, bridging the distance between what a property is today and what it will be worth when the work is complete.
For investors and developers who can see the potential in a tired or neglected property, understanding how refurbishment finance works, and critically, how to choose the right product for the type of work involved, is what makes the difference between a deal that stacks up and one that runs out of money before it gets to the finish line.
Light Versus Heavy: The Classification That Drives Everything
The single most important decision in refurbishment finance is whether the project is light or heavy. This is not just a description. It determines the product, the structure of the facility, the lender panel available, and the cost and complexity of the whole process.
Light refurbishment covers cosmetic and non-structural works. Decoration, new flooring, a kitchen or bathroom replacement, rewiring or replumbing where no structural changes are needed, minor repairs. The defining characteristic is that the works do not require planning permission or building regulations approval. A light refurbishment bridge is a relatively straightforward product. Funds are typically released as a single advance on day one, covering both the purchase and a refurbishment element, and the process from enquiry to completion can run to two or three weeks with a responsive borrower.
Heavy refurbishment covers structural work. Extensions, loft and basement conversions, internal reconfigurations, structural repairs, change of use under permitted development. The usual markers are works requiring planning permission or building regulations sign-off, or a works budget above roughly 15% to 20% of the property value. Heavy refurbishment finance is structured very differently from a light bridge: funds are released in staged drawdowns as works progress rather than as a single advance, and a monitoring surveyor is involved at each stage to certify that the work has been completed before the next tranche is released.
Getting this classification right matters more than it might seem. Running a light scheme through a heavy structure means paying monitoring costs and accepting drawdown mechanics that the project simply does not need. Running a heavy scheme through a light structure is considerably worse: the lender will not release funds for structural work it never underwrote, and the developer can find themselves mid-build, with a contractor on site and wages to pay, unable to access the next portion of their facility.
If a project sits near the boundary between light and heavy, the practical advice is to describe the actual schedule of works in detail rather than letting a broad description drive the classification. Whether a wall is load-bearing can matter more to how the finance is structured than the overall size of the budget.
How Staged Drawdown Works
For heavy refurbishment projects, the works element of the facility is released in stages across the project rather than all at once. Understanding how this works practically is important for investors planning their cash flow.
The facility is typically split into a day-one advance, based on the current value of the property, and a works facility that is drawn in tranches as construction progresses. Drawdown stages are agreed at the outset and typically align with key milestones: first fix, second fix, and completion. A £150,000 renovation fund, for example, might release £50,000 at purchase, a further £50,000 at first-fix completion, and the final £50,000 at second-fix and decoration stage.
Before each tranche is released, the monitoring surveyor inspects the property, verifies that works have been completed to the required standard and within budget, and certifies the drawdown. The lender will not release funds without that certification. Monitoring surveyor fees typically run from £1,000 to £3,000 per visit and are payable by the borrower.
There is an important cash flow implication to this structure that developers sometimes underestimate. Because staged drawdowns are released in arrears, the developer funds each stage of work before being reimbursed by the lender. That requires working capital over and above the loan facility itself, and running out of working capital mid-programme is one of the most common ways a refurbishment project stalls, regardless of how strong the underlying scheme is.
One benefit of staged drawdown, from the borrower’s perspective, is that interest only accrues on funds that have actually been drawn. On a longer project where not all capital is needed at once, this can represent a meaningful reduction in the overall interest cost compared with paying interest on the full facility from day one.
How Lenders Assess Refurbishment Finance
Lenders assessing a refurbishment finance application are looking at a different set of questions from those on a standard mortgage or even a straightforward bridging loan.
Current value and gross development value. Refurbishment lending is assessed on two valuations simultaneously. The current value of the property, in its present condition, determines the initial advance. The gross development value, which is the projected open market value of the property once works are complete, caps the total facility. The stronger lenders in this market can advance up to 72% net of the purchase price on day one, plus up to 100% of the refurbishment costs released in staged drawdowns. The binding constraint is whichever of the two LTV calculations produces the lower figure.
Schedule of works. A detailed, itemised cost schedule from a contractor or quantity surveyor is a standard requirement for heavy refurbishment applications. Vague cost estimates are not acceptable to lenders who are committing to fund a works programme in stages. The schedule needs to show what is being done, in what order, and at what cost.
Exit strategy. The lender needs to understand how the facility will be repaid before they agree to lend. For most refurbishment projects the exit is either sale of the improved property or refinance onto a standard mortgage or buy-to-let product once the property is in mortgageable condition. If the exit is refinance, the critical question is whether the take-out lender will lend at the value being assumed, at the leverage being assumed, and within the timeframe the facility allows.
Experience. Most lenders will consider first-time refurbishers on light projects, where the works are straightforward and the risk is limited. Heavy refurbishment finance, particularly for structural projects or change of use schemes, typically requires a demonstrable track record of completing similar projects. Lenders also look at the contractor involved: a main contractor with verified experience on similar projects strengthens the case considerably.
The Cost of Getting It Wrong Mid-Project
The financial risk in refurbishment finance is not just in the rate. Time is money in a way that is easy to underestimate at the planning stage. Interest runs for the entire period that the works take, not the period originally planned for them to take. A three-month overrun on a £500,000 facility at 0.75% per month adds over £11,000 to the interest cost that was never in the original appraisal, and may require a facility extension that brings its own fees.
This is why the work that happens before the first drawdown is at least as important as the build programme itself. A solid schedule of works, a credible contractor, adequate working capital, and a clear exit that has been stress-tested against realistic timescales are what separate refurbishment projects that complete on budget from those that do not.
Where Refurbishment Finance Fits in the Wider Funding Picture
Refurbishment finance does not exist in isolation. For investors buying at auction, it is often the product that makes an unmortgageable lot fundable within the 28-day completion window. For landlords converting a standard residential property into an HMO, it is the bridge between the property as a single dwelling and the licensed multi-tenancy exit. For developers working on permitted development conversions, it sits between the acquisition bridge and the eventual sale or buy-to-let refinance.
Understanding where refurbishment finance sits in the funding stack, and how it hands off to the next product in the sequence, is where a specialist whole-of-market broker adds the most value. The lender who is right for the refurbishment stage may not be the right lender for the exit, and structuring those two stages so that they connect smoothly, rather than leaving a gap between completion of the works and the ability to refinance, is what keeps investors in control of the timeline and the costs.
At GMSL, we work with investors and developers across the full range of refurbishment projects, from a light cosmetic bridge on a single property through to staged drawdown facilities on complex structural schemes. If you have a project in mind, or a property you are looking at that a high street lender has already turned down, get in touch and we will tell you straight what the options look like.